


What Is a Virtual IBAN API? A Technical Guide for Platforms Issuing Multi-Currency Accounts
October 26, 2026 by nyagyeman
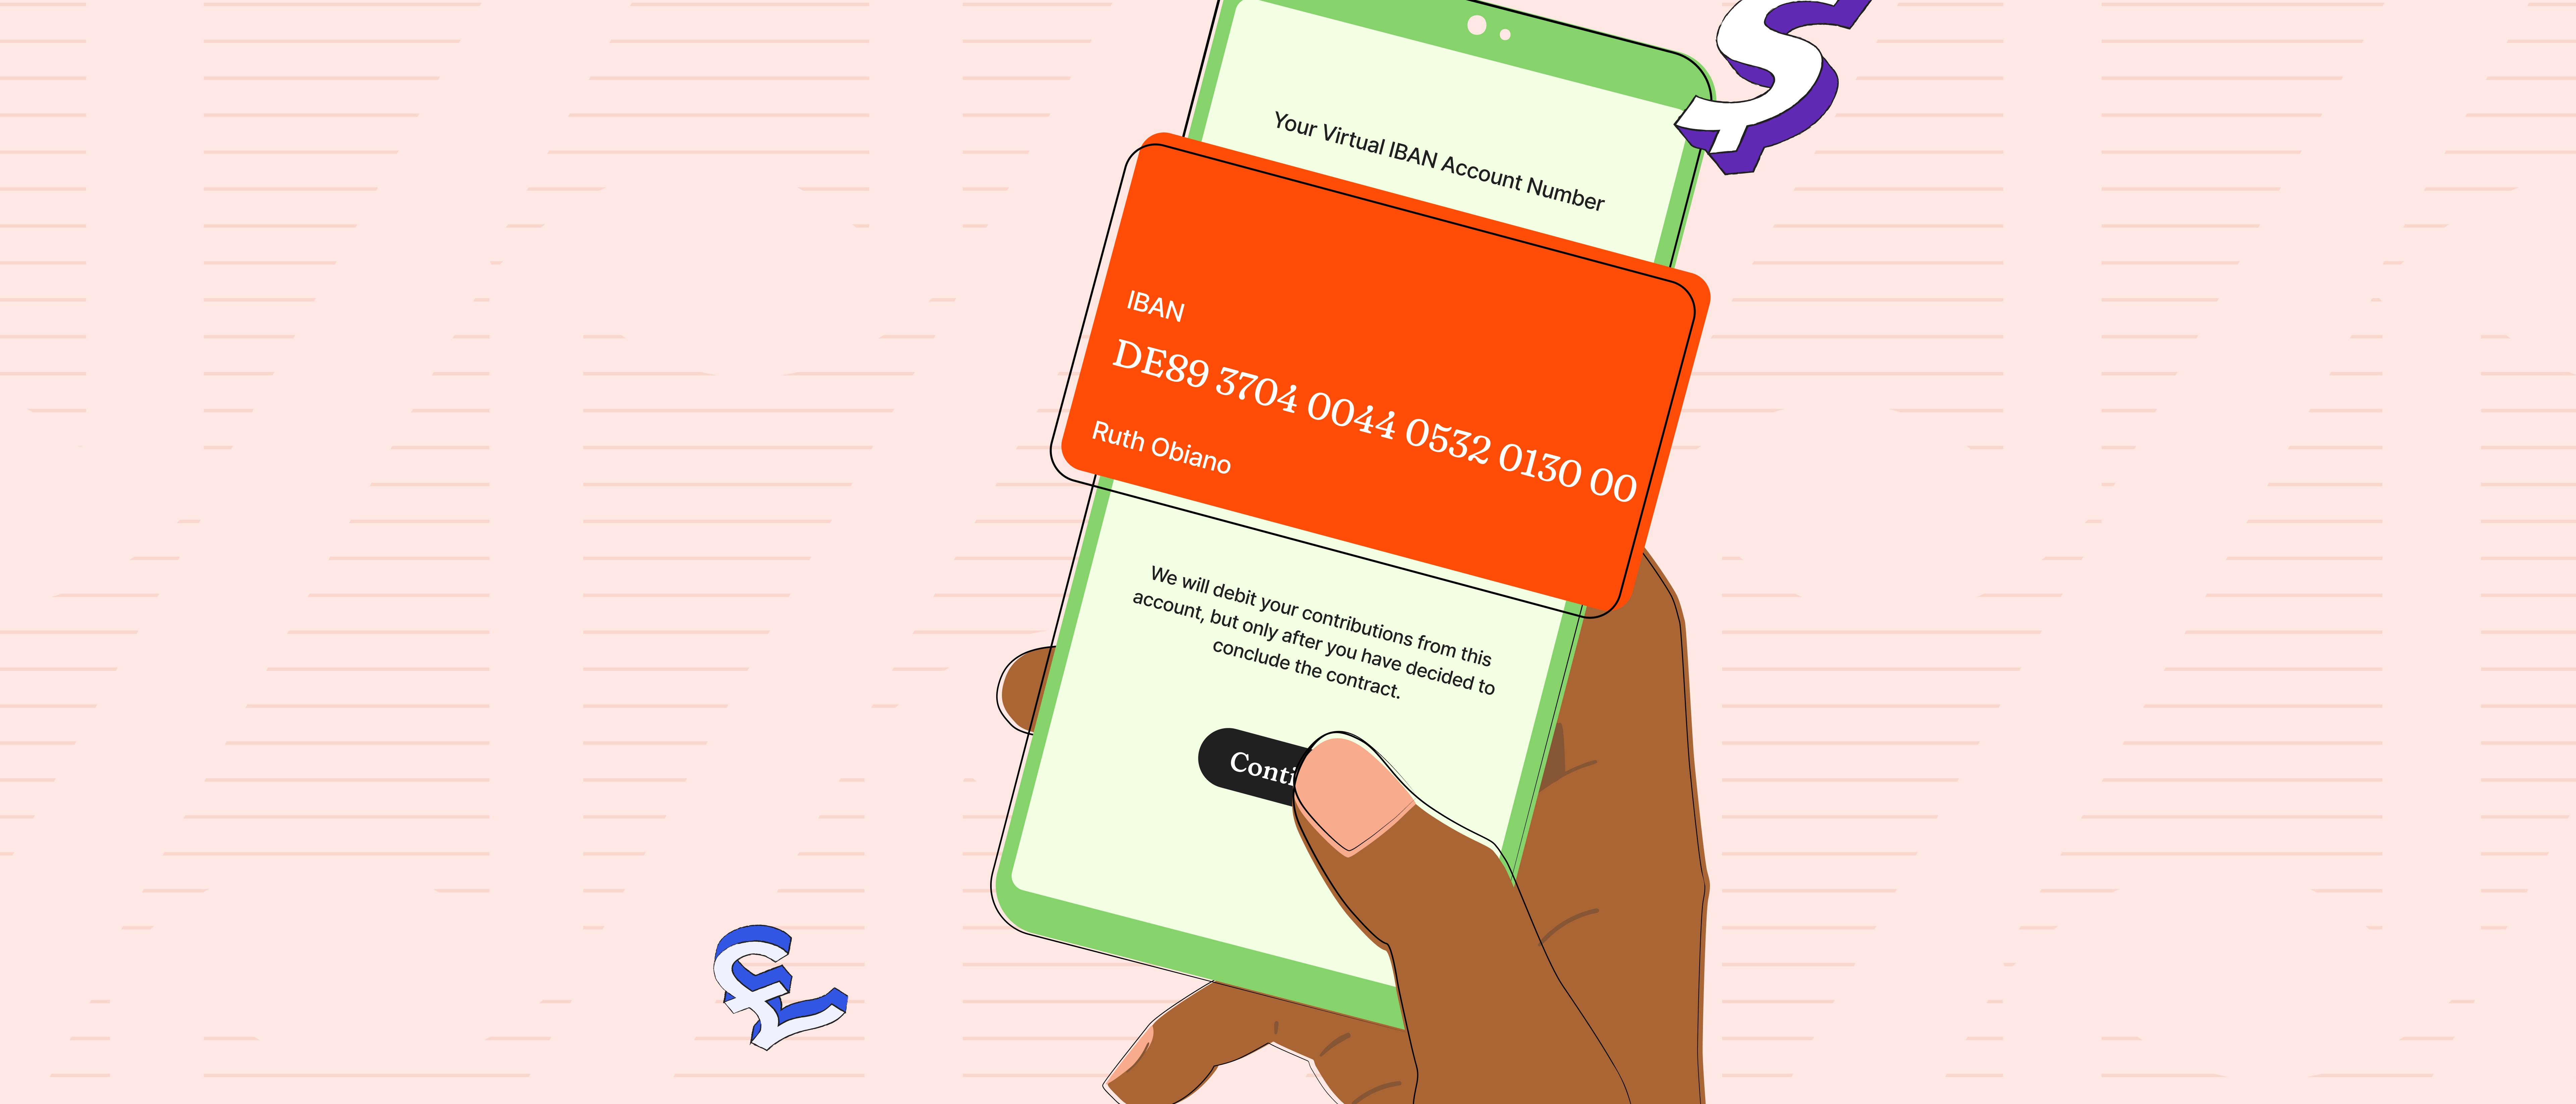
A platform decides its customers each need their own account number, not a shared pool with reference codes everyone hopes get typed correctly. The question that follows is technical: how does an account number that looks and behaves like a real IBAN get created programmatically, mapped to one specific customer, and kept in sync with a real-time balance, without the platform opening a new bank account every time a customer signs up? That’s exactly what a virtual IBAN API does.
In this guide, we will explore how virtual IBAN issuance actually works under the hood, how ownership mapping keeps every account tied to the right customer, how real-time balances stay accurate without manual reconciliation, and how this API sits as the connective layer between a virtual accounts product and the developer infrastructure powering it.
What Is a Virtual IBAN API?
An IBAN (International Bank Account Number) is a standardized identifier used in more than 80 countries to route international payments, defined by ISO 13616. A traditional IBAN maps one-to-one to a physical account at a specific bank. A virtual IBAN works differently: it’s a real, functioning account number that behaves exactly like a traditional IBAN to whoever is sending money to it, but instead of sitting in its own standalone account, it routes funds to a shared master account while retaining full identification of the specific customer it belongs to.
A virtual IBAN API is what makes this programmatic. Rather than a bank manually opening a new account for every customer, a single API call issues a new virtual IBAN, maps it to a specific customer, and makes it immediately capable of receiving payments, without the platform needing a separate banking relationship for each one.
How Issuance Actually Works
The mechanics are more automated than most people expect. The issuance process occurs entirely via API during customer onboarding: when a user signs up, the platform’s system requests a new virtual IBAN, which is instantly mapped to that user’s ID in the platform’s internal ledger. Every payment sent to that virtual IBAN routes automatically to the master account, where the system identifies the destination account and updates the correct customer’s balance without any manual intervention.
This is also inherently scalable in a way manual account opening never could be. Virtual IBANs can be provisioned programmatically via API, scaled to millions of accounts, and deactivated instantly, which is exactly the kind of elasticity a platform onboarding hundreds of new customers a month actually needs.
Ownership Mapping: Why “Named” Virtual IBANs Matter
Not every virtual IBAN implementation solves the ownership problem the same way. A named virtual IBAN is issued specifically in an individual customer’s name, creating a one-to-one relationship between that account number and exactly one customer’s balance. A pooled virtual IBAN, by contrast, uses a single account number for multiple customers and relies on reference codes in the payment description to identify which customer a given payment belongs to, thereby reintroducing the exact reconciliation risk. If a reference code is dropped or mistyped, ownership must be reconstructed manually rather than being structurally guaranteed.
Issuing virtual IBANs through named accounts avoids this entirely. The mapping between account and customer isn’t a hope that a reference code survives the payment chain intact. It’s built into the account itself from the moment it’s issued.
Real-Time Balances Without Manual Reconciliation
Because every named virtual IBAN maps to a specific customer, balance updates don’t require a separate reconciliation step. The moment a payment lands in the master account, the system identifies which virtual IBAN it was sent to and updates that customer’s balance directly, the same event-driven pattern covered elsewhere in webhook-driven architectures, applied specifically to account balances rather than transaction status.
The Bridge: Where Virtual Accounts Meet the API
This is the piece that connects two things that platforms often consider separate products. A virtual account, the kind a business opens directly through a dashboard, and a multi-currency virtual accounts API, the programmatic version a platform uses to issue accounts on behalf of its own customers, are the same underlying capability accessed in two different ways.
The account itself, its currency, its rails, its reconciliation trail, doesn’t change depending on whether it was opened through a form or provisioned by an API call.
Built on a Global Corridor, Not a Single Region
WeWire’s virtual account issuance covers USD, GBP, EUR, NGN, and GHS, provisioned via a single API call. Each account carries its own identity, transaction history, and reconciliation trail, with settlement routed through ACH, SEPA, SWIFT, or Fedwire, depending on the corridor. A platform building an IBAN API that African businesses can issue accounts through is working with the same infrastructure serving platforms across the US, Canada, the UK, and fast-growing corridors elsewhere, reaching 100+ countries in total rather than a single regional footprint.
Part of a Broader API
Virtual IBAN issuance doesn’t function in isolation. It sits alongside sub-account management, which segments issued accounts under a platform’s master relationship with isolated balances and permissions, and embedded KYC/KYB, which verifies each customer before their account goes live, all of which are accessible through the same API surface that a platform uses for programmatic payouts.
Built for Platforms Issuing at Scale
WeWire’s virtual IBAN API issues accounts in USD, GBP, EUR, NGN, and GHS via a single API call, each with its own identity and reconciliation trail, as part of infrastructure processing $3B+ in transaction volume for 3,000+ businesses across 80+ countries, spanning established markets like the US, Canada, and the UK alongside fast-growing corridors elsewhere.
For a platform choosing between opening accounts manually and issuing them programmatically for every customer who signs up, this infrastructure makes the second option not just possible but the more scalable default.
The Bottom Line
A virtual IBAN API isn’t a separate product from a virtual account; it’s the same account, issued at the speed and scale a platform actually needs when provisioning accounts for its own customers, rather than opening one for itself. Named issuance, automatic ownership mapping, and real-time balance updates aren’t optional refinements. They’re what separates a platform that can scale to thousands of accounts without a reconciliation team from one still hoping reference codes survive the payment chain intact.